2016-04-05

Speculative Fever Gone? First-Tier Home Prices Plummet, Traffic Collapses in Shanghai

Some homes in Shanghai have plunged 1.6 million yuan (14 percent) overnight in the wake of government efforts to slow the market. Traffic has declined 40 percent because about 30 percent of homebuyers were non-residents, but following the rules change, these buyers are now unable to purchase a home.
For the property market, second-hand housing market is more sensitive to changes in policy. In "Shanghai nine" effect, Shanghai has many owners have lower offer. As Pik plate, there is a substitution type of customers, the house has just set a good, second-hand housing may have been selling slowly, the result after the policy came out, the original listing 11.5 million yuan villa now willing to cut prices to sell 9.9 million yuan, but also talk about the price. Kongjiang area, second-hand housing stock little change, but look tenant significantly reduced, 30% of customers are non-resident customers Shanghai, New Deal affected can not purchase. Shanghai has the agency over the weekend revealed that most recent encounter a deserted weekend, visitors have decreased about 40% from the past few weekends.
Analysts predict prices could be plunging city-wide by October:
Director of research with policy advice Zhang Hongwei said: "The previous Shanghai property market regulatory policies from month to calculate, about seven months or so the Shanghai property market turnover fell to a low of Judging, October may be the property market turnover fell. into the trough period of time. "he believes that, in order to activate the market volume in October, housing prices because the problem or part of the financial side, the Shanghai property market is bound to be" price "or even" slashed prices "price for the amount of the situation. Minsheng Securities real estate Wenyang team predicted that the end of the Shanghai housing prices fell between 10% -15%.
A similar slowdown is underway in Shenzhen, where one broker says he made no sales in March:
After the regulation of the boot floor, under the Shenzhen property market seemingly calm surface, buyers and sellers of the game was on the rise. "After the Spring Festival this year, Shenzhen, sell the house was not as good last year, before a house to put out, and soon will be able to find a buyer, but now it is difficult." Shenzhen, a large intermediary revealed that Mr. Shaw told: "Last year house sell, my income doubled, the best month took nearly 10 million commission, but in March I can only get basic salary, because I did not contribute a single transaction. "in fact, in the interview, there is no fewer intermediaries have said that now the bank credit requirements, social security requirements also increased, with room ticket just to be less and less, lack of confidence in everyone buyers, the buyers' prevailing attitude is "just looking" again.

Affected owners had a tough bid mentality also began to shake. Shenzhen Central Plains Research Center data, in just the past week, Shenzhen has two owners to lower their offers. Among them, the owners offer Houhai area continued down 2.3%, down aspect Shekou Area 2. handedly building, Central monitoring data showed last week, pushing the sale of five properties for sale, most of the sales rate is not ideal, there are four projects sales rate of less than 70%, of which there are two project sales rate of less than 5 percent.

Midland Realty managing director of Shenzhen and Huizhou region Jiangshao Jie believes that the New Deal after landing purchasing power is expected to be reduced by one third, will have an impact on housing prices in Shenzhen within six months, or at least stabilize prices this year. However, Minsheng Securities predicts that the real estate Wenyang team, by year-end Shenzhen housing prices will have decreased by 20% -25%.
High priced homes in Beijing aren't moving after regulators threatened agents:
Beijing Homelink responsible person expressed, for the health of the sound development of the real estate market, some of them off the shelf high-priced houses, the school district where the main room. These high-priced housing to the market had a negative atmosphere, priced at more than 15 million yuan listings they will no longer sell the Commission, the Commission continues to sell the school district housing price will be not more than 150,000 yuan. However, the Yangcheng Evening News reporter yesterday queries Homelink website found that there are still individual school district housing priced at 15 million yuan.

A real estate industry said recently high priced Beijing real estate listings have been removied, up to the total number of 10,000 units. Relevant government departments recently interviewed the relevant person in charge of a number of real estate firms, real estate agency required to guarantee they are not driving up prices, otherwise Beijing will introduce relevant regulation and control policy.
Guangzhou isn't slowing much, but it also never overheated:
However, trading volume rose did not bring prices soared. The latest data show that in March the average price of net signed 18,320 yuan / square meters, the chain has a 8.11% gain. "March is the peak of the degree of housing turnover, resulting in a certain city net signed the average price rise." An agency official told reporters that although the property market soared case, there are many non-degree housing owners fare sale room, but the rate of increase is usually about 3% to 5%, far lower than previously north, the deep easily several hundred thousand dollars to hundreds of million of the increase.

Thus, house prices in Guangzhou and these three cities more pull away. Data show that second-hand square aspect, February, Shenzhen, the average transaction price 48,000 yuan / square meter, Shanghai average transaction price of 26,000 yuan / square meters, the Beijing average transaction price reached 39,000 yuan / square meter, while the Guangzhou only 16,900 yuan / square meter. To this end, Guangzhou cities does not guarantee the status of the voice heard. However, stable housing prices in Guangzhou has won the praise of many users, users do this as "the most rational of the city."

iFeng: 一线楼市现“退烧”信号 有房源一夜跌160万

SCMP No Longer Has Paywall

Alibaba has dropped the paywall at SCMP.

Bear Market Rally in CNY Almost Over

FT: Renminbi bears rethink currency bets
“The renminbi is controlled and it will be controlled. It’s not a free market; the PBoC is the biggest player and we all know that,” says one senior banker at a mainland institution, who doesn’t expect more dramatic moves this year.

According to a survey by Reuters of non-deliverable forward positions — one way short bets are expressed — investors are still slightly short renminbi, but those positions are less than a quarter of their January peaks.
That tallies with anecdotal reports from bank trading desks and hedge fund brokers.

“There are medium-term funds that went into 2016 with short-China as a relatively core position and it hasn’t performed — however, it probably hasn’t caused enough pain to be restrictive,” says Asher Williams, head of rates and macro sales at Société Générale for Asia-Pacific ex-Japan.
Increasing the value of CNYUSD solves the issue of short-term speculative outflows and depreciation bets, but it makes taking money out of China more attractive because it can buy more overseas assets. If the current economic and outflow trends are not short-term in nature, the PBoC's actions have increased the odds of depreciation over the long-term.

One can't forget about the U.S. dollar. USDCNY is outperforming USDEUR, USDCAD, UDSAUD, USDJPY...and some of those foreign currencies have recovered their losses all the way back to August 2015. CNYUSD is still below its August 2015 levels. Big rallies in most non-USD currencies, but not a big rally in CNYUSD. CNY decouples from USD when USD is strong, and recouples when USD is weak.

2016-04-04

8 Economic Trends Chinese Govt Expects in 2016: Slower Wage Growth, More CPI Inflation, Less PPI Deflation and Greater Yuan Volatility

Eight things the NDRC expects for 2016:

1. Slight acceleration in CPI (higher inflation)
2. PPI deflation will slow
3. GDP deflator will shrink
4. Agricultural price inflation will decelerate
5. Real estate differentiation will continue and price increases will be larger than last year:
From the perspective of the development, with the favorable policies to further show the effect of multiple, local real estate market rigid demand and improving demand further release, the real estate prices form a strong support, annual real estate prices will remain clear upward trend, may be more than last year.
6. Slight RMB depreciation will continue, with greater volatility
7. Price of money will decline
8. Wage growth will slow

iFeng: 预计中国2016年房价涨幅超去年 通胀率更高

Chinese Market Expects Another RRR Cut in April; Credit Risk Rising

Background from January:

Reuters: China cash injections could substitute for RRR cut - c.bank economist
Moves by China's central bank to inject over 600 billion yuan ($91.19 billion) in liquidity ahead of the Lunar New Year holidays could substitute for a cut in the amount of cash that banks must hold as reserves, the chief economist at the People's Bank of China(PROC) was quoted a paper as saying on Thursday.

Ma Jun told the China Business News in an interview that PBOC's liquidity injections could "imply a substitute for a cut in banks' reserve retirement ratios (RRR)".
China's RRR cut on March 1 was estimated to release about 700 billion yuan in liquidity, but the PBoC drained more than 1 trillion yuan.

Xinhua: 3月净回笼超万亿 降准预期升温
In early March the central bank lowering quasi release of liquidity of about 700 billion yuan, but the end of March, the central bank in the open market net return of 1.085 trillion yuan in a single month. And drop quasi hedge, the central bank still achieve a net monthly return of more than 300 billion yuan, ending two months of continuously adding liquidity.

In this regard, gold purse chief analyst Xiao Lei believes that the net return to the open market in April RRR opened window. Affected reverse repurchase expired, March drained the open market, reducing market liquidity, which is the April drop quasi expected presence of one reason, but served less than the base currency is the main reason. Before the central bank mainly through the foreign exchange base money, but with dwindling foreign exchange and reduce the central bank base money channels.

It is worth noting that the central bank released data show the end of March, the end of February, foreign currency forward contracts for currency futures contracts and long positions in $ 2.438 billion, $ 28.9 billion of short positions. Xiao Lei believes that the data show that the central bank in managing the exchange rate is weapons, which countries and how much you want to save the city announced its own stock index futures held more than a single empty one is a reason.
Credit risk is rising as well: 信用风险升温 期债波动加剧
Frequent events of default

March 28, Dongbei Special Steel announcement failed to pay in full payment "15 East Steel CP001" principal and interest, constituted a material breach, becoming the first local state-owned enterprises raised bond debt default event. This year, bond defaults just three months last year exceeded the sum, but without excessive pessimism. Nanjing rain this month default run short melt finally obtained main load-bearing support liquidity crisis temporarily lifted. Early breach YABANG investment, Zibo Hongda were deferred payment. In the credit crisis spread on the occasion, the bond credit spreads may widen, need to focus on liquidity shocks generated by a large area of default risk.

Since the early 5-year bond futures premium is more, the recent sharp premium convergence, plus 5-year cash bond market is stronger than the 10-year period, the yield curve is not steep in Treasury futures to be reflected in the contract, the recent 5 year bond futures also strengthened this phenomenon has been amended.

We believe that the current tight market funds is a temporary phenomenon, but in April the financial side fluctuation still not be taken lightly. In the short term, higher inflation, risk appetite, the bond market has some pressing need to closely monitor the impact of credit debt default events. Long-term view, monetary policy has not changed and can hardly be improved on the fundamentals of the bond market will support, debt cattle trend entirely. High and volatile bond market is expected to exacerbate.

Copper Price Action, Fundamentals Still Weak

Reuters: Connecting the dots between weak copper demand growth and prices
"There's a disparity between prices and fundamentals. A reckoning is overdue," a source at a commodity trading house told Reuters ahead of the Cesco copper conference in Santiago.

"(Chinese) cable producers are not expecting a pick up in demand from the (power) grid, property funds are bearish and the inventory of air conditioners is huge, in the region of 40 million units, about 10 months supply."

The State Grid Corporation of China (SGCC) in the final quarter of 2015 went on a spree, buying cables to use up its budget, but that only cannibalized orders in the first quarter of this year, sources say.

SGCC has said it plans to cut investment to 439 billion yuan this year, down from 452.1 billion in 2015.
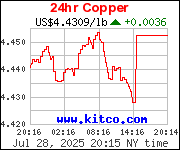
Respect the price action. The current rally is a big one, but it hasn't broken the downtrend begun in mid-2005.

Even If GDP Gap Closes, Lack of Innovation Will Keep China From Becoming Developed Nation

This article by Li Xunlei discusses China's lack of innovation and why even if China achieves high income status (about a 50% increase in per capita GDP from current levels) it still may not qualify as fully developed.

2015, China's GDP reached 67.67 trillion, per capita GDP was 49,351 yuan, even though according to 1: 6.2 exchange rate basis, or less than $ 8,000. If the next five years the average annual nominal GDP growth rate of 7%, the US dollar against the RMB exchange rate at the current level of 1: 6.5 remain unchanged, the per capita GDP 2020 was $ 10,400, still with the high income of $ 12616 national threshold is not a small gap.

So, the next decade China should always entered the ranks of high-income countries, right? It may not. If the next decade, the average growth rate of nominal GDP to 6% (15-year 6.3 per cent), in 2025 the US dollar against the RMB exchange rate is 1: 7, the per capita GDP in 2025 was $ 12,100, or not entered high income threshold countries. Even if the economic situation over the next decade than assumed good, real GNI per capita of more than $ 12616, but do not rule out raise income countries on the World Bank standards possible.
China can grind its way to high income at present growth rates (but do you believe official numbers...), but that doesn't mean there aren't problems.
Therefore, the future of China to become a high-income countries, there were three major obstacles:

First, the future ability to maintain GDP growth of around 6% level.
No surprises to China watchers, but he gives three reasons for why slower than expected growth is possible:
In fact, I have always thought that the Chinese economy should see three dimensions, one demographic factors (labor supply and consumer demand), two structural factors (the degree of match between the factors of production), three environmental factors (the global economy) . Currently, the status of these three dimensions is not optimistic.
Next the currency:
Second, whether the RMB exchange rate remained stable.

...the ability to stabilize the exchange rate at 7:1 also doubtful.
The target is also moving:
Third, the high-income countries will raise the standard over the next decade.

...The next decade, as governments around the world compete to adopt looser monetary policy, money flooding phenomenon is difficult to change, so, 10 years after the high-income countries to US $ 14 000 standard is a conservative estimate.
The article goes on to discuss the structure of the Chinese economy, the continued reliance on fixed asset investment and lack of innovation. The cost of investment is rising, requiring ever more credit growth to achieve the same level of GDP growth. This leads to a cycle that ends in currency devaluation:
High GDP growth> high investment> easy Money> high debt> Fiscal deficit> assets shift from real to imaginary> asset misallocation> asset bubbles> inflation> devalue.
Li then looks at local economies:
Although we should have been declared China an innovation-driven economy. Although the Chinese economy has bright spots of innovation, but innovation contribute much, how high technology content, the statistics speak for themselves.

NBS 15 years of statistical bulletin, add a data, that is, high-tech industrial investment 3.2598 trillion yuan, an increase of 17.0%, accounting for investment in fixed assets (excluding rural households) accounted for 5.9%. The so-called high-tech industry investment, including pharmaceutical manufacturing, aerospace vehicles and equipment manufacturing, and other six major categories of high-tech manufacturing and investment information services, e-commerce services and other nine categories of high-tech services investments.

Low proportion of high-tech industry investment, also shows that China is still very far away from the innovation-driven stage. Although China's Internet industry is developing rapidly, but are bigger transactions or information platforms, such as BAT, Jingdong, Ctrip and so on. Investment in fixed assets, the majority of investments are low, both short-term or long-term rate of return on rate of return is very low. If a high rate of return, the corporate debt should not grow rapidly.

We therefore compared with developed countries, the gap is still very large. For example, in the national provincial Tianjin region, the per capita GDP of the first, but this is mainly driven by investment, the proportion of investment in GDP is too high, while the per capita disposable income is much lower than the deep north. Chongqing has the same problem, a high GDP growth rate, but fixed asset investment accounted for more than 90% of GDP, actually, did not attract huge investment and population concentration, population but is in outflow.

Shenzhen is the only developed country in the crowd were shoulder to shoulder, the added value such as high-tech industry in Shenzhen 15 years created GDP ratio reached 32 percent, modern accounting services to 39%. Shanghai mainly by financial , real estate, automobile manufacturing and other traditional advantages and economic advantages of agglomeration, high-tech industry contribution to GDP is not large.
This chart alone can make the argument: it shows fixed asset investment as a share of GDP.
Shenzhen is the only truly innovative city major city, with Shanghai relying on its status as financial center and Beijing on government. The next chart shows the push to change the economy has been failing for over a decade, with the share of investment rising at the same rate as areas such as the West, which lagged behind in development and was targeted for massive infrastructure investment.
The only bright spot is the uptick in the northeast after the economy began to slow substantially in 2014, though the implication for the Chinese economy is not positive if rebalancing means fixed asset investment suddenly collapses and drags GDP lower with it.

Li closes with a comparison to the Great Leap Forward:
If the only goal is to have GDP catch up with the Anglo-American standard, it seems to have similarities with the Great Leap Forward and the people all smelting steel. Even if the GDP were to catch up, we are still lagging behind in many other aspects. In fact, since the reform and opening up, China has done great, as long as we adhere to being people-centered, narrow the gap between rich and poor, it has been pretty good so far.
iFeng: GDP高增长真相:中国离发达国家还有多远?

Why Migrant Workers Save Their Money and Go Home

When people think of rural houses in China, be they Chinese or foreigners, they think of this house below.
Not all rural residents are poor though. Consider this house below.
The house cost 200,000 yuan for 200 square meters, or 1,000 yuan per square meter to build. The article doesn't say when it was built, but the price gap with first-tier cities is probably wider today than it was when it was built.

iFeng: 农村房的前世今生

Brexit Preview: Holland Votes on EU-Ukraine Policy

Breitbart: UKIP’s Nigel Farage In Amsterdam For WEDNESDAY’S Little Known Dutch EU Referendum
The referendum is only the second in the country’s recent history, and will ask members of the Dutch public if they support the EU’s 2014 association agreement with Ukraine – a document widely believed by eurosceptics to have provoked Russian action against EU expansionism.
EU officials may realize the political project is unpopular at the moment, since they didn't campaign on the issue:
Carnegie Europe: No Dutch Courage for Ukraine
If the EU believes the EU-Ukraine Association Agreement is a good thing—and already, 27 of the 28 member states have ratified it—then EU leaders should have campaigned for it ahead of the Dutch vote. The argument that this would be interfering in the internal affairs of another country is disingenuous. This is a European issue.

Not only that. Over the past few months, the no campaign has mutated from focusing on the democratic deficit in the EU to criticizing Ukraine’s endemic corruption and spreading (unfounded) fears that the accord would give Ukrainians the right to work in the EU.
Brexit supporters could get a boost from a Dutch vote against the deal, since it will show that other Europeans are opposed to the EU. Pro-EU supporters conflate the political project with Europe itself, but as Brian Monteith points out, the Dutch may shatter this illusion.

Scotsman: Brian Monteith: Dutch vote may be start of the EU’s decline
The ill-will towards detached and distant EU politicians that this ­episode generated remains and there is a strong possibility that the Dutch government, campaigning in favour of the EU-Ukraine Association Agreement, could lose.

If that does happen it will be noticed in the UK and cited as evidence that dissatisfaction with the European Union is not confined to the EU but is Europe-wide.

This is important for it clashes with the mythmaking of the Remain ­campaign that to feel a European, indeed to stay in Europe, you have to be in favour of the European Union and be a member.

2016-04-03

House Flipping is Dead in Wenzhou

Although Wenzhou's property market has started to revive, house flippers aren't making money, with small profit margins if they're lucky. The article below is long, going through the history of Wenzhou's property market back to 1998 and through the bubble that peaked in 2011. Below is the coverage of the current market:
2015 Year of the Ram at the beginning, some of the real estate agent has re-opened, it seems the market is expected to have improved markedly. Wang also clearly felt, friends around buyers confidence restored. According to reports, last year, Wenzhou city's 5.27 million square meters of commercial housing turnover, the urban second-hand housing turnover 1.96 million square meters, nearly 2 million units, are historical highs.

Although transactions beautiful, but after a year of operation, Wang found that real estate is no profit margin.

Wang said most of the Wenzhou real estate speculators still apply, only a few real estate speculators get out. Chen started to open stores, usually on the economic issues of great concern. In 2010, Chen sold the entire investment in real estate, Wenzhou, bring their wives and children the family moved to Hangzhou, and encourage friends around the big city to buy a house. Today, he accompany their children abroad to study life, enjoy themselves at the same time, more concerned about the stock market, foreign exchange and other capital markets.

Chen's view is that the proportion of financing is too large, high financial costs, although housing prices doubled before, but real estate speculators who trade frequently limited profit. Once stuck, if house prices had fallen by four percent, plus interest and other financial costs, real estate speculators are mostly insolvent.

An analyst at Guotai Junan Securities believes that the market economy stood in the forefront of Zhejiang Province, the local government and the people should not think most taxpayers' money to pay for these speculators, so the government did not take what real money to bail out the crisis, but central to fight for a financial reform pilot qualifications. After that, Wenzhou will enter a long and painful process of deleveraging passive, banks almost threw himself at the disposal of indigestion, companies are starting to issue bankruptcy cancer in clearing.

People's Bank branch in Wenzhou city Latest data show that the end of February this year, the city's local and foreign currency deposits for the first time exceeded one trillion mark, reaching 1.0051 trillion yuan; individual housing loans 105.91 billion yuan, accounting for 13.72% of total loans balance, an increase of 3.52 billion compared to the beginning yuan. In addition, the impact of the economic environment, loan growth of private enterprises and individual industrial and commercial households has slowed.

See reflected conceivable whole picture, Wenzhou sample is no longer unique.

In the hands of the high investment whirlpool, Lao Wang, and many investors are aware, it is the accumulation of dangerous bubble, the problem only when you should withdraw. At the same time, the lever and speculators to join, not only from the actual value of the real estate expanded, resulting in more traditional industries in Wenzhou "off real to imaginary," is tantamount to economic harm Qiaoguxisui.

China's economy is currently in a critical period "to the old sterile new" industrial transformation and upgrading, shared development, real estate market needs a smooth, balanced and healthy development. 13 years of ups and downs of real estate and huge economic losses, let Lao Wang know, housing prices have soared lost soil environment, "mainly housing inventory, the traditional business survival difficult, young buyers desire to weaken the asset allocation to Capital Market , real estate has come to the end."
iFeng: 温州老王13年楼市浮沉:“炒房已经到了末日”

Another Unfinished Nightmare: City of Excavators Becomes City of Unfinished Buildings, Construction Continued for 3 Years

Zhangjiajie in Hubei Province (a popular tourist spot) is another example of the ongoing bursting of China's real estate bubble. The city was said to be filled with excavators in 2013 as construction boomed. Today it is sitting on 21 months of inventory after the market froze in 2013. The city had supply-demand ratio of 246.7% back in 2014, third highest of the 70 cities in the widely reported monthly NBS price survey. The number was originally reported here in 2014: China Home Buyers Underwater; More Ghost Cities Emerge
However, local supply and demand imbalance cities such as Yingkou, Ordos, Zhangjiajie supply and demand ratio reached 476.6%, 385.4%, 246.7%, storms of such property or the city will be difficult to avoid.
The city was also listed as tenth most likely to experience a crisis back in 2014: Chinese Cities Most Likely to Suffer A Housing Market Crash
10. Zhangjiajie, Hunan (张家界)
9. Qingyang, Gansu (庆阳)
8. Yan'an, Shaanxi (延安)
7. Pingliang, Gansu (平凉)
6. Guyuan, Ningxia (固原)
5. Ordos, Inner Mongolia (鄂尔多斯)
4. Dingxi, Gansu (定西)
3. Jiuquan, Gansu (酒泉)
2. Wuwei, Gansu (武威)
1. Longnan, Gansu (陇南)

This number is much worse today worse because inventory is still rising and sales are still falling, but media is still using the that old 2014 figure (which is likely based on 2013 data):
According to Zhangjiajie City People's Government website data, the city's commercial housing sale area 680,800 square meters, an increase of 5.5% yoy, of which sale residential area of ​​546,400 square meters, an increase of 52.8% yoy.

At the same time, Zhangjiajie City real estate sales area and sales amount of downward trend was on the rise. 2015 to November area of ​​419,500 square meters of commercial housing sales, down 15.6% yoy, the sales amount of 1.55 billion yuan, down 32.5% yoy.
The fact that problems which emerged in 2013 have only gotten worse, reminds me of the recent post on Jincheng (China's Credit Nightmare Unfolding in Jincheng), I wrote:
I've covered trust defaults and credit guarantee blow ups since they started popping up in 2013. Nearly all of them went away, but I wonder how much of that was due to extend and pretend, versus an actual clean up of the situation. If it was extend and pretend, swapping new debt for old, then the zombie industries are truly the tip of the iceberg, with all manner of unforeseen debt problems lurking beneath should credit conditions deteriorate.
Below, we find real estate problems weren't solved either, with one developer in Zhangjiajie having run away back in 2013. This makes me wonder how many of the individual local real estate collapses, credit cooperative failures, credit guarantee implosions, trust failures and ghost cities covered on this blog over the years are still extant problems.

China bulls and bears alike are generally in agreement that China has the ability to "solve" problems by government fiat (such as financial repression), and most articles covering local real estate or financial collapse mention the government formed a work group to solve the problem. The bullish view says costs get shifted but growth goes on, while bears believe the costs eventually show up in slowed GDP growth, slower lending, currency depreciation, etc. Yet the recent stories show even many bears may have been too optimistic, that actual full blown crises may have been swept under the rug in the hopes that growth would solve them. If this is the case, there are not only zombie steel mills and zombie coal mines, but zombie economies and zombie governments.

After the jump are two individual cases from the iFeng article on Zhangjiajie.

China's PPT Top 10 Shareholder in Majority of Firms; Industrials and Smaller Companies Dominate

China's National Team (plunge protection team) ended 2015 as a top ten shareholder in 698 firms out of 1298 reporting year-end results, or 53 percent.

The total PPT investment comes to 800 billion yuan in companies with a colective market value of 2.5 trillion.

Most holdings are in firms with market caps of 10 to 30 billion yuan, with the PPT holding a top 10 stake in 313 of these firms, or 43 percent of the total.

Industrial firms account for 20.5 percent of the total, the largest single industry.

These figures exclude investments made prior to the PPT effort and only represents the holdings in companies that have reported year-end 2015 results. At the end of 2015 Q3, the PPT held shares in 1363 companies. Goldman Sachs and BofA estimated the PPT invested a total of 1.5 trillion yuan. Both figures are in line with current figures, as half the market has yet to report.
Reporters already disclosed in 2015 annual report 1298 listed companies combing found that teams in the top ten tradable shares of listed companies in the amount of 698. In the perspective of the number of shares and the market value of statistics, market capitalization of 500 billion yuan has 72 (accounting for 10.32%), market capitalization between 30 billion -400 million there are 76 (accounting for 10.89%), while the market capitalization stock between 10 billion 30 billion have 313 (accounting for 44.83%), 50 to 10 billion market capitalization of the stock with 165 (accounting for 23.64%), 50 billion with market capitalization of the stock with 72 (accounting for 10.32%).

From the industry perspective points to the CSRC industry (new) standards division, 67 (accounting for 9.6%) belong to the consumer food business sector, 58 (accounting for 8.3%) belong to the extractive steel non-ferrous metal plates, 101 (accounting ratio of 14.5%) belongs to the real estate and decoration materials industry, 67 (accounting for 9.6%) belongs to the TMT industry, 143 (accounting for 20.5%) belongs to the industrial manufacturing industry, the pharmaceutical sector 67 (accounting for 9.6%), the financial sector 45 house (accounting for 6.5%).

From six months ago (to March 31, 2016 as the base to push forward) earnings point of view, there are 329 listed companies in the 30 times price-earnings ratio, which is equivalent to 47% of the historical stock price-earnings ratio below 30 times; accounting for 30 times to 40 times between 13.6%; accounting for 40 times -60 times between 13.5%; accounting for more than 60 times price-earnings ratio of 25.8%.

Guangzhou, a private equity firm partner told the "China Times" reporter, he was more concerned about the national team for small and medium ticket situation positions. "Me and some of my fellow like excavation team holding more small ticket. Last year's third quarter, the top ten shareholders only several small ticket almost every team, these stocks usually have good gains, but need ahead of the layout. "The private partner analysis says.
iFeng: 国家队持股全景图:8000亿家底大曝光 制造业最受青睐
This data is very illuminating for the ChiNext analog. The PPT at times focused on lifting the value of large companies in the Shanghai market in order to move the headline index, but they also focused on small companies where the impact of buying has a far greater effect on individual stock prices.

Chinese Youth Don't Want to Live in Urban Graveyards

Rows of empty buildings serve as the tombstones for China's 2008 stimulus. They're a constant reminder of housing inventory which will keep home prices suppressed for years, as well as bad debts which impair the local economy, as many locals are ensnared by the bursting of the bubble. Slowing local economies deliver the final blow, as third- and fourth-tier cities struggle to retain their youth population. In some cities, net migration is negative. Young people are leaveing for the larger and wealthier cities, such as Beijing. Even mighty Tangshan, the wealthiest city in Hebei per capita, is not immune.

Reuters: China hits property policy jam as regional market gap widens
For the 18th consecutive month, home prices in Tangshan fell in February from a year earlier, official data showed.

It is littered with unfinished buildings - Reuters counted at least 10 such housing projects there last week - and each one represents countless individual misfortunes, as developers abandon projects and run off with downpayments.

On one ghost development called "Youth Zone", a lifeless block set in withered grass, graffiti on a steel door into the site reads: "Give me back my home".

A 50-year-old investor who gave her surname as Ma said four years ago she made a downpayment of 120,000 yuan ($18,400), several years of savings, for a new apartment on another project. Soon after, it ground to a halt and the developer went missing, along with her money.

"There aren't many people around in Tangshan who haven't been caught in a property trap in recent years," she said.
A Chinese article relaying the Reuters piece digs into the story further. Tangshan is in the heart of the rustbelt recession, with a large steel industry. It's also not far from Beijing and Tianjin, two wealthier and more attractive cities for the young:

iFeng: 外媒称三四线城市楼市去库存难:年轻人都去了大城市
Although Tangshan, Hebei Province is a leading economic powerhouse, with per capita GDP ranked first in the province, the many unfinished buildings give Tangshan people misgivings about buying; and this heavy industries such as steel and coal city famous, yet failed attract too many new public demand. Since it's only a half hour to Beijing by high speed rail, Tangshan has lost a lot of young people.

Brexit Takes the Lead

2016-04-01

Shenzhen Existing Homes Sales Surge Ahead of Tax Hike

Shenzhen is reducing the time between assessments to six months as of April 1. The shorter gap between assessments could cause taxes to rise 50% to 100% based on recent home price increases, which would represent a significant rise in taxes for short-term speculators. Additionally, transaction taxes will rise. This looming tax hike led to a surge in sales ahead of the increase:
According to the Shenzhen Centaline research center monitoring, Shenzhen March existing housing turnover of 18,706 units, a substantial increase of 120%, closing an area of ​​about 1.6 million square meters, a month-on-month surge of 136%, a record high. At the same time, the price rise, the average price of second-hand up to 56,149 yuan / square meters, the month-on-month surged 6.75 percent, the largest increase since July 2015.
New home sales, which aren't affected by the tax changes, went in the other direction last month:
Yishoufang regard, subject to policy control is expected, trading volume fell sharply. According to the Shenzhen Centaline research center monitoring March 4461 sets of residential sales, a decline of 17.5%, closing an area of ​​464,800 square meters, a decline of 17%. For the next three months Shenzhen market situation, the industry is widely expected, due to policy tightening, new home transactions will weaken in the coming months.

iFeng: 深圳楼市调控再放大招 二手房交易税费大幅上调

Trade War Begins: China Slaps Duties on Japan, EU and Korea Steel

Look for this type of tariff to be met with more retaliation, not less. The game has changed from deescalation to escalation.

Mofcom: 商务部公布对原产于日本、韩国和欧盟的进口取向电工钢反倾销调查初裁决定
April 1, 2016, the Commerce Department released 2016 No. 10 Announcement , published originating in Japan , South Korea and the European Union's import-oriented electrical steel anti-dumping investigation of the preliminary decision.

Commerce Department finds originated in Japan, South Korea and the European Union's import-oriented electrical steel dumping, domestic-oriented electrical steel industry has been substantial damage, and the causal relationship between the dumping and material injury, and decided to implement the product in the form of provisional anti-dumping margin measures. According to the preliminary decision, import operator at the time of importation of the above sources and should provide the appropriate premium to the Chinese Customs in accordance with each company's preliminary decision determined the dumping margin (14.5% -46.3%).

ChiNext Analog Remains Elevated

Beijing 9070 Policy Expected to Return, Langfang Developers Halt Sales

Beijing is expected to bring back the 9070 regulation from 2006, which states 70% of new home construction must be of houses smaller than 90 square meters.

At February 24 over one month ago, the Shanghai property market regulation to increase the efforts made to increase the proportion of small and medium size housing supply, not less than 70% of the central city, suburban, not less than 60%.

According to data provided by Centaline Property, the real estate market from the current structure, 90 square meters of housing inventory in Beijing only 1.9 million units, accounting for 31% of the total housing stock overall total; from inventory accounting area, the current Beijing city 90 small units accounted for only 13.8% of square meters; then from the turnover ratio, the current first quarter of 2016, the city's auction structure 90 square meters dwelling size accounted for only 16.7%.

Overall, the Beijing real estate market has been the trend of high-end, many more tend to improve customer turnover. Just need to improve the customer first and have basically concentrated in the secondary housing market, the first quarter of 2016, Beijing commercial housing turnover average single cover an area up to 137 square meters.

Beijing, a local real estate industry to the "Daily Economic News" reporter revealed that the small size products and the supply of trading volume than the smaller, causing the concern of regulators, the next step depends on the Government's plan for how out.
iFeng: 北京楼市调控风起:90/70政策或重出江湖

In Langfang, developers have halted sales as they await new housing rules.

The so-called "north county", namely Langfang City, Hebei Province under the jurisdiction of Sanhe City, Dachang Hui Autonomous County and Xianghe County, three counties belonging to the administrative Langfang City, was in position on the ground is real tight on Beijing and Tianjin package real, Beijing recently called "back garden." Since the beginning of the special position of the ground, the Beijing market regulation policy from the hot market area Central Beijing, Langfang brunt will to curb housing prices through the "north county" to implement a comprehensive credit limit and integral settled.

Although the news has not heard from official sources, but in the actual trading process has almost come true. "Has been signed in the past two days, waiting for the network to sign, the developer called me yesterday, said it might want to pause for two days, landing and other new government initiatives."
Prices near Beijing are already up nearly 100%:
Chief analyst at Centaline Dawei opinion, Langfang near Beijing Yanjiao other regions already close to 100% price increase, in which case the introduction of housing prices rose logical, "is expected next Langfang, principal policy would be to limit price increases + credit policy constraints."
iFeng: 大厂等地房企已暂停售房 等待新的政策落地

Ha Jiming: You Can't Grow M2 By 14 pc Annually And Not Devalue

A phase change in understanding China's monetary system is underway. Nothing has changed materially, more economists are willing to publicly state what was predicted by independent economists, hedge fund investors and this blog several years ago, namely that inflation eventually leads to currency devaluation and China has been printing like crazy.

The latest is Goldman Ha Jiming who states to obvious: if you growth the money supply at 14 percent annually, the currency can't not devalue. He gives the example of the supermarkets and housing. Think about how much you could buy at the supermarket for 100 yuan a few years ago versus today. Think about how much house you could buy for 1 or 2 million yuan versus today. He goes on to say, if the currency doesn't devalue and China continues growing the money supply at 14% annually, then in a few years China can buy the whole world simply by printing money. That's not going to happen, so either M2 growth rate falls or the yuan depreciates.

This is the very point made on this blog many times before, deflation or depreciation. Last year, M2 growth fell slightly below 10% annualized for two months. The real estate market was rolling over and the northeast in recession. At 10% annualized growth, the currency is still inflating at a healthy clip. What are the odds M2 is allowed to slow to a peak of 8%, let alone something lower that would tip the economy into a full blown depression?

Steve Keen recently published an article with a simple credit based model of Australia's economy. As he puts it:
The logic is pretty simple: your spending in a year is the total of what you earn plus what you borrow, and the same maths applies to the economy as a whole.

If nominal GDP grows this year at the 2.8 per cent rate it has averaged for the last five years, then GDP in 2016 will be roughly $1,634 billion. If private debt continues to grow at its average rate of 6.9 per cent per year, it will reach $3,414 billion — an increase of $220 billion over the year. Total private sector demand (which is spent on both goods and services and asset purchases) will be $1,855 billion.

What about 2017, if private debt grows at the same rate as GDP itself, so that the debt ratio stabilises? Then GDP will be $1,680bn, and private debt will rise from $3,414bn to $3,509bn — an increase of just $96bn over the year (compared to $220bn the year before). The sum of the two will be $1,775bn — 4.3 per cent less than the year before.

This is the inevitable debt crunch coming Australia’s way, but conventional economists are oblivious to this danger because they’ve brainwashed themselves to ignore private debt as just a “pure redistribution”, to quote Ben Bernanke. This deluded textbook thinking is why Bernanke didn’t see the GFC coming.
China is no different. If debt growth stabilizes, there will be a depression. If debt growth doesn't stabilize, then the currency depreciates.

Ha Jiming doesn't see a one-off devaluation coming and he believes the country can keep the currency stable in the short-term. I suspect the short-term is much shorter than most realize.

iFeng: 哈继铭:M2每年14%的增长 人民币不可能不贬值

China's Credit Nightmare Unfolding in Jincheng

The story below is about the coal industry in one small city of 2.2 million people (300,000 in the city proper) in Shanxi. The headline is the collapse of the coal industry, but the real story is a pattern of financing that repeats all over China, from Sichuan to Hebei, from Handan to Hangzhou.

Quartz: China’s coal companies are so desperate, they’ve started farming to keep employees busy
In an unusual attempt to prevent more protests, some of China’s biggest coal mining companies are now focusing on other businesses entirely, Chinese media reports. Coal mining companies in Jincheng, a city in north China’s Shanxi province have embraced pharmacies, solar power stations, restaurants, supermarkets, and vegetable and fruit planting, National Business Daily (link in Chinese) reported on Mar. 28.
What do coal miners know about pharmaceuticals and solar power? Nothing, but it keeps people employed. At least with New Deal in America, there was a temporary aspect to many projects. It's unclear how these coal mines are funding these ventures or if they're expected to last more than a few years.
But that’s not the worst part. Some Chinese coal firms are even faking their earnings to borrow from banks, Economic Information Daily reported (link in Chinese) on Mar. 29. An unnamed executive told the newspaper his company recorded a net loss of 1 billion yuan ($155 million) last year, but faked a 50 million yuan profit in order to extend their bank loans. “Coal firms are having a hard time in the next three to five years,” the company head said, adding “many firms probably won’t make through this year.”
It gets even better. I went to read the Chinese source article and came across this article 山西五大煤炭集团负债率82% 兄弟矿相互拆借较普遍 which says Shanxi miners are giving each other short-term loans to stay in business.

This is similar to the steel trading cases a few years ago and the situation in Xiaoshan in 2014 (Rumored Mass Death of Companies in Xiaoshan District of Hangzhou If Banks Collect on Debts; Government Tells Banks to Sit Tight or Leave), where the entire entire city's economy was pushed to the edge of collapse by mutual credit guarantees. This is typical across local economies and industries in China. Many firms are mutually connected via a web of credit. This is also the situation in Jincheng, Shanxi, where even the profitable coal mines are now going bankrupt due to their lending practices:
Jincheng, a local coal industry insider even told reporters that since many coal mines cannot get bank loans and can only lend to each other, there are a number of profitable coal mines due to excessive lending other coal mines have run into funding problems, "mines earning a little money by lending have now lent themselves into bankruptcy."
The lending is taking place within larger corporate entities as well:
A finance staff Gaoping City Branch Energy Development Group Co., Ltd. subsidiary mine told the "Daily Economic News reporter," starting two years ago, some subsidiary coal mines were unable to borrow, even if the parent company guaranteed the debt, "two years ago in our company, another subsidiary coal mine borrowed 30 million yuan, said they would repay the loan in seven days, it has been nearly two years and they haven't repaid anything, we let the parent company demand repayment and they received nothing."

In fact, coal loans difficult situation in early 2014 appeared. Jincheng in the government work report for 2015, the arrangements for the new year's work had suggested that "to encourage the best use of coal enterprises to help various financing means, do everything possible to protect the coal business capital chain."

..."Two years ago, when the loan is not so tight, mines refinance old debt with new debt, but......this year Gaoping City Bank called in 500 million yuan in loans from a mine, and they cannot borrow another penny. Some mines are no longer unable to pay wages or borrow money, only to earn a little by lending to other mines, from tens of millions to hundreds of millions, and some mines have almost lent themselves to death."
What is the real cost of cleaning up zombie companies once all the secondary and tertiary industries with mutual loans and credit guarantees are added to the total? I have to believe Jincheng is like other cities where the debt risk was not isolated in the coal sector. Somewhere, perhaps the mining equipment supplier, is a conduit for contagion that could entangle one or more industries in the city. The worst case scenario is a situation like Xiaoshan, where much of the local economy was ensnared by defaults in 2014.

I've covered trust defaults and credit guarantee blow ups since they started popping up in 2014. Nearly all of them went away, but I wonder how much of that was due to extend and pretend, versus an actual clean up of the situation. If it was extend and pretend, swapping new debt for old, then the zombie industries are truly the tip of the iceberg, with all manner of unforeseen debt problems lurking beneath should credit conditions deteriorate.
"There is no means of avoiding a final collapse of a boom brought about by credit expansion. The alternative is only whether the crisis should come sooner as a result of a voluntary abandonment of further credit expansion or later as a final and total catastrophe of the currency system involved."

Ludwig von Mises